タグ: 不動産市場 (Houston Market)

  • 山積する委員会への訴訟

    不動産業界は現在、全米の消費者や規制当局からの多方面からの訴訟に直面しており、最終的にどのような結果になるかはまだ分かりませんが、業界は大規模な混乱への備えを強めています。

    シッツァー | バーネット
    シッツァー | バーネット事件はミズーリ州で10月に裁判が行われ、つい最近判決が出たため、最近最も注目を集めています。 陪審は最終的にこの訴訟で住宅販売者原告側に有利な判決を下し、全米不動産協会(NAR)とさまざまな大手フランチャイザーが共謀して手数料を高く維持したとの認識で一致しました。 問題となっていたのは、参加規則としても知られる NAR の協力報酬規則で、不動産業者提携の MLS にリスティングを提出するために、リスティング ブローカーはバイヤー ブローカーに報酬を提供することを義務付けています。 陪審は17億8,531万872ドルの損害賠償を命じたが、法律に基づき自動的に3倍の53億5,600万ドルに増額される。
    判決後の数日間で、テキサス不動産協会、ヒューストン不動産協会、メトロテックス、ABOR、その他多くの不動産会社、さらには個人エージェントに対する訴訟を含む、いくつかの「模倣」訴訟が起こりました。 NARはシッツァー・バーネット訴訟で敗訴したばかりだが、この訴訟ではNARの名前は挙げられていない。 対象となるのは、NAR MLS規則の遵守を監督したとして有罪であると主張する州および地方団体のみです。 潜在的に、この訴訟は集団訴訟の地位を求め、2019年11月13日から現在まで地元協会の物件仲介業者を利用し、買主代理手数料を支払ったテキサス州の住宅販売者を代表する可能性があります。 NARは現行の協力補償制度を擁護し、住宅をより高額で販売できるようになり、買い手により多くの選択肢を提供し、透明で効率的な市場を促進することで、売り手と買い手の双方に利益をもたらすと述べています。 NAR は、複雑な住宅購入プロセスにおいて不動産業者が顧客にもたらす価値を重視しています。
    これはあくまでも私の意見ですが、売主がエージェントの手数料を支払い、買い手エージェントと手数料を折半する現在のシステムを変更した場合、今後どのようなシステムになるのでしょうか? 売主が売り手エージェントに支払うことを約束し、今後は買い手のエージェントに直接支払うことになるニューヨークに倣うのでしょうか? 売主がエージェントに支払いをすることが多く、エージェントが中間に立って売主を代表し、買主を助けるだけ(買い手のエージェントは存在しない)というコロラドのシステムに変更するのでしょうか? 売主は売り手のエージェントに支払い、買主がそれぞれのエージェントに手数料を支払う日本のシステムに変更するのでしょうか? これらの訴訟が解決された後にシステムがどのようになるかについては、多くの選択肢があります。

    The real estate industry is currently facing a multi-front assault from consumers and regulators across the U.S. And while it remains to be seen what will ultimately happen, the industry is increasingly bracing for major disruption.
     
    Sitzer | Burnett
    Sitzer | Burnett has been the highest profile case lately because it went to trial in October in Missouri and the verdict was recently reached. A jury ultimately ruled in favor of the homeseller-plaintiffs in the case, agreeing that the National Association of Realtors (NAR) and various large franchisors conspired to keep commissions high. At issue was NAR’s cooperative compensation rule, also known as the Participation Rule, which requires listing brokers to make an offer of compensation to buyer brokers in order to submit a listing to a Realtor-affiliated MLS. The jury awarded $1,785,310,872 in damages, which, under the law, will be automatically trebled to $5.356 billion.

    In the days following the verdict, several ‘copy cat’ lawsuits have come out, including a suit against Texas Realtors, HAR, MetroTex, ABOR, and many other real estate companies and even individual agents. Although NAR just lost the Sitzer Burnett case, it is not named in this suit. The target is only state and local associations saying they are guilty for overseeing compliance with the NAR MLS rules. Potentially, this lawsuit could seek class action status and represent home sellers in Texas from Nov 13, 2019 to present, who used a local association’s listing broker and paid a buyer’s agent commission. NAR defended the current system of cooperative compensation, stating it benefits both sellers and buyers by allowing homes to be sold for more, providing more choices for buyers, and facilitating transparent and efficient marketplaces. NAR emphasizes the value Realtors bring to clients during the complex homebuying process.

    This is my opinion only, but if we change the current system where sellers pay their listing agent and their listing agent splits their commission with the cooperating buyer’s agent, then what system will we go to?  Will we follow New York, where sellers are committed to paying their listing agent and will now pay the buyer’s agent directly?  Will we change to a Colorado system where the seller often pays their listing agent and the listing agent is in the middle, representing the seller and just helps the the buyer (with no buyer’s agent)?  Will we change to a Japanese system where the seller pays the listing agent and the buyer pays his own agent? There are many options of what the system could become after these lawsuits are worked out.
  • 案浦不動産最新情報

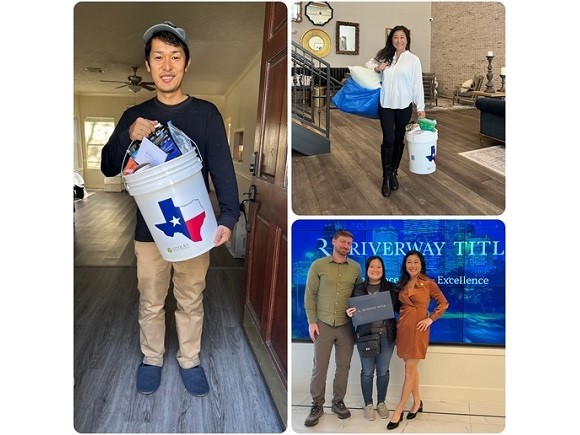
    金利が昨年と比較し2倍となっており、最近の不動産市場はとても慎重に扱われています。買主は30年間8%に固定することに躊躇しており、売主は3%の抵当に入っている家を売却して2倍以上の価格で別の住宅を購入することに躊躇しています。売主が販売を再検討するため在庫は減少し、買主が最初は少しの間レンタルに徐々に移行するため、買主の数も減少しています。弊社は、販売物件のうち 2 軒の販売を完了させることができました!医療センター内のタウンハウスは先週の金曜日に、クリア レイクの一戸建て住宅は本日販売完了となりました。ファーナム・パークにある浸水した邸宅はオプション期間を無事に乗り越え、買い手の融資が承認されるかという次の課題に直面することになります。Olympic Forest(www.har.com/38788420)はまだ適格な買い手を探しており、デイモンの物件(www.har.com/89982771)も市場で何が起こるかを見極めている段階です。賃貸の面では、日本政府の新しい駐在員が週末に新居に引っ越しました。彼の申請料と手続き料が免除され、さらに 1 か月間家賃が無料になるという交渉をしました。クラレ駐在員は週末にクリア レイクの家に引っ越し、 MD アンダーソン研究者はメディカル センター内のアパートに申請を完了しました。新たに三井物産の駐在員とパナソニックの新たな駐在員の新居探しのお手伝いも始まる予定です。利上げが一時停止される中、セール面でのさらなる行動が期待されます。ヒューストンへの購入、売却、賃貸、または移住を希望している方をご存知ですか?知弊社まで是非お問い合わせください!

    With interest rates double what they were last year, the market is quite cautious these days. Buyers are hesitant to pull the trigger and lock into 30 years of 8% while sellers are hesitant to sell their 3% mortgaged house and buy something else at more than double. Inventory is lower as sellers re-think selling, and buyers are fewer as buyers slowly shift to renting for a little while first. That being said, we were super excited to see two of our sale listings close recently: the townhouse in the medical center closed last Friday and the single family home in Clear Lake sold today! The flooded mansion on Farnham Park made it through the option period and will face its next challenge of the buyer’s financing getting approved. The home on Olympic Forest (www.har.com/38788420) is still looking for a qualified buyer and our listing in Damon (www.har.com/89982771) is also riding out the market to see what might happen. On the leasing front, our newest expat with the Japanese Government moved in over the weekend to his new home. We were super excited to be able to get his application and administration fees waived PLUS negotiate one full month free for him. Our newest Kuraray expat moved into his Clear Lake house over the weekend, and our newest MD Anderson researcher chose an apartment in the Medical Center. The past two weeks has been very productive! On the horizon is a new Mitsui expat and a possible new Panasonic expat. We are hopeful for more action on the sale front with the interest rate hike on pause. Fingers crossed! Who do you know that might want to buy, sell, lease, or move to Houston?  Let us know!

  • 陪審員、ランドマークシッツァーの住宅販売者に50億ドルを授与

    先日、大手不動産会社が住宅販売コストの吊り上げを共謀したとして告発された訴訟で、住宅所有者に53億6,000万ドルの賠償を与える判決を下しました。裁判は2週間続き、約2時間半審議した結果となりました。この訴訟にはミズーリ州の約50万人の住宅所有者が関与しており、購入仲介業者に手数料として支払った17億8000万ドルの返還を求めていました。陪審は彼らに17億8000万ドルを与えましたが、法律に基づいて3倍の53億6000万ドルに達することになります。

    この訴訟は、全米不動産協会と大手不動産会社が不動産手数料率の引き上げに協力したかどうかをめぐって展開されたものです。陪審は、これらの金利を引き上げる陰謀が確かに存在し、これが住宅所有者に悪影響を及ぼしたと結論を付けました。この訴訟の被告には、NAR、Keller Williams、Anywhere (旧 Realogy)、RE/MAX、HomeServices of America、および、その子会社 2 社が含まれていました。

    この結果、住宅所有者が不動産サービスに対してより多くの費用を支払ったことを意味する可能性があります。 NARは判決を不服として控訴し、損害賠償の軽減を図る予定となっています。彼らは、ガイドラインによって不動産市場の透明性と公平性が確保されていると主張しているが、今回の件は将来的に住宅購入者に重大な影響を与える可能性があり、住宅購入の複雑なプロセスで専門家の支援を受けることが難しくなる可能性があります。

    In a major decision, a jury recently awarded $5.36 billion to homeowners in a case that accused major real estate companies of conspiring to raise the cost of selling homes. The trial lasted two weeks, and the jury deliberated for about two and a half hours before making their surprising decision. The lawsuit involved around 500,000 homeowners in Missouri who were seeking to get back $1.78 billion they paid in commissions to buyer brokers. The jury gave them $1.78 billion, which will be tripled under the law to reach $5.36 billion.

    The case revolved around whether the National Association of Realtors and big real estate companies worked together to increase real estate commission rates. The jury concluded that there was indeed a conspiracy to raise these rates, and this affected the homeowners negatively. The defendants in the case included NAR, Keller Williams, Anywhere (formerly Realogy), RE/MAX, HomeServices of America, and two of its subsidiaries.

    The verdict could mean that homeowners paid more for real estate services due to this conspiracy. The NAR plans to appeal the decision and try to reduce the damages. They argue that their guidelines ensure transparency and fairness in the real estate market, but the case could have significant implications for homebuyers in the future, potentially making it harder for them to get professional help during the complex process of buying a home.

  • ヒューストン市場の現状

    金利が上昇する中売買するのが魅力的ではない中、ヒューストンの不動産市場は今どうなっているのでしょうか?! 弊社の売却物件5軒のうち、4軒が現在契約中です。 しかし、5軒目は、現在何が起こっているかを説明する良い例かもしれません。 オーナーは現在 4% という低金利を享受しています。 もし売却した場合、別の家に引っ越してローンを組み、7.5%の金利を支払わなければなりません。 これは大幅な増加であり、彼にとって魅力的ではありません。 むしろ、彼は今の場所に留まり、引っ越しをしない傾向があり、その結果、私たちは家を市場から引き揚げることになりました。 この市場からの上場撤退はヒューストンでは現在少なくなりました。 HAR.com の最新の統計によると、昨年の第 41 週 (10 月 10 ~ 16 日) と比較して、撤退した物件の数は 12% 増加しました。 市場に出回った新規物件に関しては、第 41 週には昨年と比べてより多くの売り手が物件を売却しようとしており、その数は実際に 9.4% 増加しました。 データによると、昨年と比較して保留中の販売額は 7.4% 減少しており、実際に購入者が見つかった住宅の数が少ないことを意味しています。 最後に、成約についてはどうですか? 実際に最終決定テーブルに残ったのは? この数字も 15.1% 減少しており、これはかなり大きな数字です。 これは、昨年の今時期と比較して、より多くの売り手が販売に努め、成功した売り手は少なく、実際に決算テーブルに残ることはさらに少ないことを示しています。 逆に、クロージングテーブルに進出できれば、すごいことです!

    With the high interest rates making it not attractive to purchase or sell, where is the Houston Real Estate Market now?! Of our 5 listings, four are actually under contract. But the fifth, may be a good example to illustrate what’s happening right now. The owner currently enjoys a low 4% interest rate. If he sells, he will have to move to another house and get a loan and pay a 7.5% interest rate.  That’s a huge increase and not attractive to him. Instead, he is more inclinced to stay at his current place and not move, causing us to pull the home from the market. This withdrawing of the listing from the market is happening quite a bit in Houston. The latest statistics from HAR.com show that compared to week 41 of last year (Oct 10-16), the number of withdrawn properties was 12% higher. As for brand new listings hitting the market, numbers were actually UP 9.4% with more sellers trying to sell their properties compared to last year in week 41. Were they successful in actually selling though?  No, because the data shows that compared to last year, pending sales were DOWN 7.4%, meaning less homes actually found buyers. Finally, what about closings? How many home actually made it to the closing table? That number is also DOWN 15.1% which is fairly significant. This shows us that more sellers are trying to sell, less are successful, and even less than that actually make it to the closing table, compared to this time last year. On the flip side, if you DO make it to the closing table, it’s a major feat! Celebrate!!

  • 住宅ローン金利は上昇を続ける

    住宅ローン金利は先週、7.31%と23年ぶりの高水準を付けたが、今週も7.49%と高止まりしました。この情報は、フレディ マックの主要住宅ローン市場調査から得られたものです。

    今週の数字は以下のとおりです。

    30年固定金利住宅ローン金利は7.49%で、前週の7.31%から上昇しました。 1年前は6.66%でした。

    15年固定金利住宅ローン金利は6.78%で、前週の6.72%から上昇し、1年前は5.90%でした。

    専門家は、こうした高金利はインフレ、雇用市場の変化、連邦準備制度がこれからどうするかについての不確実性などの要因によるものだと考えています。こうした高い金利により、住宅を購入する人が減少しています。

    また、低金利で購入し後々変更できる変動金利住宅ローン(ARM)の人気が高まっていると指摘しています。住宅建設業者は買い手を引き付けるために低い金利を提供しており、売り手は買い手が金利を下げるために成約費用の手当を提供するなど、住宅ローン金利を下げる取引を行っています。

    住宅ローン金利が約6%に下がるには2024年末までかかる可能性があるため、買い手も売り手も来年は高金利が予想され、譲歩や交渉がより一般的になると推測されています。

    Last week, mortgage rates hit a 23-year high at 7.31%, and this week they remained high at 7.49%. This information comes from Freddie Mac’s Primary Mortgage Market Survey.

    Here are this week’s numbers:

    • The 30-year fixed-rate mortgage is at 7.49%, up from 7.31% last week. A year ago, it was 6.66%.
    • The 15-year fixed-rate mortgage is at 6.78%, up from 6.72% last week. A year ago, it was 5.90%.

    Experts believe these high rates are due to factors like inflation, job market changes, and uncertainty about what the Federal Reserve will do next. These high rates are causing fewer people to buy homes.

    Experts also note that adjustable-rate mortgages (ARMs), which start with lower rates but can change later, are becoming more popular. Homebuilders are offering lower interest rates to attract buyers, and sellers are making deals to lower mortgage rates, such as offering closing cost allowances to help the buyer buy down the rate.

    It might take until the end of 2024 for mortgage rates to come down to around 6%, so both buyers and sellers should expect high rates for the next year, with concessions and negotiations becoming more much more common.