Mortgage rates have doubled to over 7% since the Fed raised interest rates in 2022.
At a rate of 7%, the median monthly mortgage payment for a $392,200 home is roughly $2,800, near a record high, according to a Redfin analysis. At a rate of 3%, that monthly payment would be close to $1,800.
This makes buying a home less affordable, with monthly payments for a median-priced home nearly double what they were at 3% rates, according to a Redfin analysis.
Historically, 6% mortgage rates are normal, but very low rates during the pandemic spoiled many buyers.
Fannie Mae doesn’t expect rates to return to 3% in our lifetimes but predicts a more normal range of 4.5% to 6% in the coming years.
Fannie Mae forecasts rates to fall below 7% as early as the start of next year, with home price growth also slowing down.
The law is changing and starting August 17, 2024, all realtors and their clients will be affected. This change in business practice is the result of a lawsuit against the the National Association of Realtors. Until now, it was fairly common to work with a buyer to find a house without requiring the buyer to sign a ‘Buyer Representation Agreement”. A buyer would simply contact a realtor and the realtor would help them find a house to buy. The new rules state that before the realtor can show that buyer any homes, the buyer will have to first sign a Buyer Representation Agreement, which will bind the buyer to pay for his agent’s commission, with the amount negotiable between the parties. Until now, it was customary for the seller to pay commissions to his own realtor (the listing agent), who would then offer a portion of this commission (usually half) to any cooperating realtor who would bring a buyer. Because of this, the buyer did not have to pay any commissions to his agent. The buyer’s agent would be paid by the seller’s agent, and all the commission money would actually come from the seller. The offer of commission was denoted on HAR.com so that the public and all realtors could see it and know how much it was. However, starting August 17, the MLS (for Houston, HAR.com) will no longer be allowed to display the offer of commission, so this field will be removed. Before showing any homes, the buyer’s agent will need to call the agents of all the homes the buyer wants to see, to verify if the seller will help the buyer pay for the buyer agent’s commission. It is highly anticipated that the seller will still offer a ‘buyer’s concession’ to help the buyer pay for his agent’s commission. They know that if they do not, the number of buyers that can see the home could be drastically limited, as many buyers barely have money for their down payment and can not afford to pay the buyer agent’s commission. It is important to note that if the seller says he will not offer a buyer’s concession, the buyer will then have to decide whether or not they still want to see the house. In the case where the seller will not offer a buyer’s concession to help the buyer pay for the buyer agent’s commission, and if the buyer does not have money to pay for the buyer’s agent’s commission, then that house would either not be shown or the Buyer Representation Agreement would have to be revised before it can be shown. Needless to say, the process to show houses to buyers will become a much more difficult and time consuming process, and could potentially cost the buyer a significantly higher cost if they have to pay their own realtor’s commissions. HAR.com has made these videos to help the illustrate the changes: https://cms.har.com/the-reality/.
Well, I just saw my homeowners insurance renewal come through and it is crazy high! I have read in so many different publications that homeowners insurance is becoming a major problem throughout the country for homeowners. In some places in Florida and California, insurance companies are leaving the market and not offering insurance policies at all anymore. At the same time, the insurance companies who ARE staying in the game have increased their premiums sometimes 2-3 times their previous rates. This is causing trouble for homeowners who can no longer afford insurance, but have to have it because they have a mortgage (loan) and the lender of course requires it. Sometimes this leads to the homeowner having to sell the home. High insurance premiums and high interest rates have created an environment where a lot of people are shifting to renting instead of owning homes. It is an affordability issue that has only worsened because of the lack of affordable homes to buy. A recent news article commented that now in 90% of local market in the U.S. it has actually become cheaper to rent than to own a home! Younger people polled commented that they were happy renting apartments because they did not need to be tied to a long mortgage and because they had the flexibility to move wherever they wanted without having to be tied to a home in the same city for years and years. Wow, maybe the American dream is changing?!
The latest numbers are out and this is a great place to share them with you! These are the numbers from HAR.com, who tracks all the housing data in Houston each month. New listings were up 4% compared to March 2022 while Active listings were way up, increasing 22.6%. An active listing is where a listing is sitting on the market for sale, not under contract yet. The fact that they were up 22.6% shows that the market may be slowing down with less active buyers to put them under contract. Interesting though, the average list price did NOT go down! Conversely, list prices were UP 2.2% compared to March of last year. The average list price for a single family home in Houston right now is $428,048, compared to to $419,023 last year.
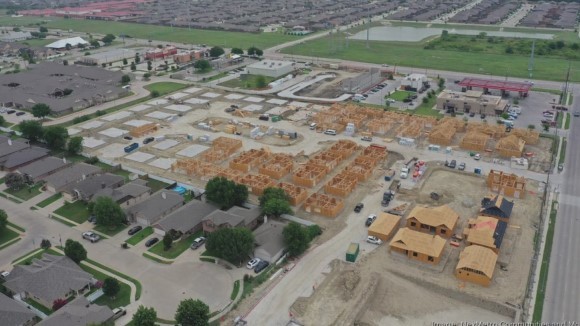
There is a new trend in the real estate market. It is called BTR, Built to Rent. Bascially, home builders will buy and develop an entire subdivision but will not sell each house retail to the general public. Instead, they build with the intent to rent ONLY. Once all the homes are rented, they often sell the entire subdivision to institutional investors or funds. With home prices rising and rising and interest rates also high, buyers are turning into renters. The latest news pertaining to BTRs in Texas was summarized by The Real Deal news source. Dallas Fort Worth is the second best market in the USA. Here are some other findings:
Built-to-rent (BTR) trend is becoming increasingly prominent in real estate, particularly in Texas.
Dallas-Fort Worth ranks as the second-largest BTR market in the US, with Houston at third and Austin at sixth.
Majority of single-family built-to-rent starts in 2023 were concentrated in the South, with 61 percent of them.
D.R. Horton, a major homebuilder, has heavily invested in the BTR market, selling over 4,000 rental homes to Pretium Partners for approximately $1.5 billion.
Lennar, another significant player, launched a $4 billion BTR investment platform in 2021.
Financially, BTR units make sense due to lower costs compared to mortgages. The monthly rent for single-family BTR units ranges from $2,000 to $2,500, with a significant difference from mortgage payments.