Demand for mortgages (home loans) from homebuyers dropped to its lowest point since 1995. This is because interest rates are rising, which makes people worried about inflation and causes the Federal Reserve to consider raising rates for a longer period of time. The number of existing home sales also decreased by 2.2 percent from June to July alone, and was a signficant 16.6 percent lower compared to last year. This is because there are not enough homes available for sale and the mortgage rates are not favorable for buyers. According to the Mortgage Bankers Association, the average rate for a 30-year fixed-rate conforming mortgage increased to 7.31 percent from 7.16 percent the previous week. Wow!
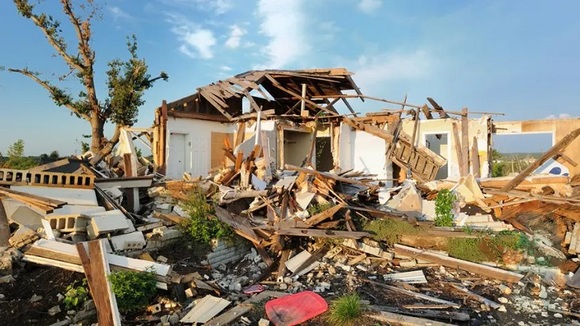
Home insurance companies are reducing the coverage they offer in areas that are at high risk for extreme weather events. This is because the insurance companies believe that climate change is causing more frequent and severe weather patterns. A survey conducted by the National Association of Insurance Commissioners found that policies will no longer cover damage caused by hurricanes, wind, and hail in coastal areas and regions prone to wildfires. Allstate plans to limit new policies in hurricane-prone areas and may have specific deductibles or exclusions for wind and hail damage. Recent extreme weather events, such as Hurricane Idalia and Tropical Storm Hilary, have caused significant damage in several states. There have also been costly wildfires in Maui. Over the past three years, insurance companies in the US have paid a record $295.8 billion for natural disaster claims. In the first half of 2023 alone, there were $40 billion in insured losses due to natural disasters, making it one of the most expensive first halves on record. Climate change is causing changes in weather patterns, resulting in longer wildfire seasons, more frequent and intense hurricanes, and a shift in tornado-prone areas. Some homeowners are unable to find insurance coverage, and state governments are having to step in to provide coverage as a last resort. This is resulting in homeowners having difficulty finding insurance and new homebuyers having difficulty buying a home for the first time.
Some of the nation’s largest insurance companies such as State Farm and Allstate have ceased writing policies in states with the highest natural disaster risks, for example, California, Florida, Colorado, and Louisiana. The insurance division of AAA said recently that it would not renew policies in Florida that it considered had “higher exposure,” and Farmers stated that it will not offer new policies in Florida and will not renew thousands of existing policies in part because of increasing losses from hurricanes. Millions of homeowners across the country now must find different kinds of coverage, which are usually more expensive and cover less. If people have a mortgage on the property, then the mortgage company almost always requires insurance. The United States is “marching steadily towards an uninsurable future,” says Dave Jones, a law professor at the University of California, Berkeley and the state’s former insurance commissioner. This will impact lending, construction, and real estate overall. In Colorado and Texas, the average cost of home insurance has increased by about 40 percent since 2015, and Florida has seen a 57 percent increase during the same period. In 2021, Chubb said it was scaling back writing policies in areas of California that were even moderately exposed to wildfire risks. AIG, State Farm, Farmers, and Allstate followed Chubb’s lead. With the global heat wave continuing, temperatures are reaching a point that will make climate impacts like heat and storms much more destructive. The takeaway: Expect higher and higher insurance premiums when purchasing homes, qualifying for loans, and at renewal time.
Roughly 14 of every 1,000 U.S. homes changed hands during the first six months of 2023, according to a new report from Redfin (redfin.com), the technology-powered real estate brokerage. That’s down from 19 of every 1,000 during the same period of 2019 and the lowest turnover rate in at least a decade. What does this mean? Sellers are not selling, they are holding on to their homes. House hunters searching for large homes in the suburbs have seen the biggest drop in their options. Just about 16 of every 1,000 four-bedroom-plus suburban single-family homes sold in the first half of this year, down from 24 of every 1,000 that sold in the same period in 2019. That means buyers of 4BR single family homes in the suburbs, have 33% fewer houses to choose from. Smaller houses in the city actually have an even lower turnover rate. Roughly 11 of every 1,000 two- and three-bedroom single-family homes in urban neighborhoods sold in the first six months of 2023. This means compared to last year (which was 14 out of every 1000), there just aren’t many 2BR-3BR homes available to buy in most of the major cities in America right now.
An article from Realty Times shared by HAR CEO Bob Hale revealed that about 70% of renters are not even considering purchasing a home right now. This will strengthen the rental market and is a positive for landlords
Many analysts—and NAR—believe that prices will continue to rise during the remainder of the year, as home prices rose 2.5 percent in April but note, the average single-family sales price was actually down 1.6 percent in Houston in May (and down 1.3 percent in April) According to the survey, the top 7 reasons for renters not wanting to buy are:
Don’t want the responsibility of taking on a mortgage
Prefer renting
Worries about job security
A separate Zillow survey showed that 52 percent of Gen Z and 57 percent of Millennials who don’t currently own a home believed they would need to win the lottery to be able to afford a home. Zillow has characterized the current housing affordability as the worst in at least 15 years. With current rates and prices, a buyer would need to save about $67,000 to afford a 20% down payment on a typical home in the U.S. That is on top of the $431 per month more that has been added to the average mortgage payment due to rising prices and mortgage interest rates.