タグ: 住宅購入・売却 (Buying & Selling)

  • 案浦不動産最新情報

    四半期目の最初の 1 か月が半ばを迎え、過去 2 週間のほとんどは契約交渉に費やされました。 私たちのリスティングは 1 つずつ契約に基づいていきました (サイプレス ポンド、カントリー グリーン、マルワース、ファーナム パーク)。しかし、それは単なる始まりにしかすぎません。 契約から成約までには 通常4 ~ 6 週間かかりますが、この期間中には 突破しなければならない2つの難関なハードルがあります。 一つは検査、もう一つは評価です。 これらのハードルのいずれかが契約を破滅させる可能性があります。 サイプレスポンドは両難関を通過し、先週の木曜日19日に無事売却完了となりました。 カントリー・グリーンは検査を通過し、現在鑑定書が届くのを待っている。マルワースも検査を通過し、鑑定書が届くのを待っている。一方、最もエキサイティングなニュースは、ファーナム・パークが先週契約を結んだことだ。 まだ初期段階にありますが、2週間後の次のニュースレターまでに良いニュースをお届けできることを期待しています。 駐在員さんのニュースでは、真理子はINPEXからの新しい駐在員さんのアパート入居のお手伝いしました。 そして、もう1人の入居プロセスのお手伝い中です。 そして、申請手続きがほぼ完了した新しいMayekawa駐在員の対応も担当しています。 今週は、ダイキンから新しい入居者が数件あり、金曜日には日本総領事館からも駐在員さんを迎える予定です。 日本からは投資家の山田さんも遊びに来てくれます!

    Halfway through the first month of Q3 is where we are in the year! Most of the past two weeks was working through contract negotiations. One by one, our listings went under contract (Cypress Pond, Country Green, Mulworth, Farnham Park), but that is just the beginning! It takes 4-6 weeks to get from contract to close and there are usually two tough hurdles. One is the inspection and one is the appraisal. Either one of those hurdles can blow up the deal. Cypress Pond made it through both and closed last Thursday the 19th. Country Green made it through inspections and is now waiting for the appraisal to come in. Mulworth made it through inspections and also waiting for the appraisl to come in. Meanwhile, the most exciting news of all is Farnham Park went under contract last week. We are still in early stages but hope to have good news by the next newsletter in two weeks. In expat relocation news, Mariko helped an Inpex newcomer move into her new apartment. She is also working on helping a second Inpex expat. Mariko is also handling a new Mayekawa expat who is nearly done with the application process. Coming up this week we have several new Daikin move-ins and a newcomer from the Japanese Consulate this Friday. We also have an investor from Japan, Mr. Yamada, coming to visit us!
  • 住宅ローン金利は上昇を続ける

    住宅ローン金利は先週、7.31%と23年ぶりの高水準を付けたが、今週も7.49%と高止まりしました。この情報は、フレディ マックの主要住宅ローン市場調査から得られたものです。

    今週の数字は以下のとおりです。

    30年固定金利住宅ローン金利は7.49%で、前週の7.31%から上昇しました。 1年前は6.66%でした。

    15年固定金利住宅ローン金利は6.78%で、前週の6.72%から上昇し、1年前は5.90%でした。

    専門家は、こうした高金利はインフレ、雇用市場の変化、連邦準備制度がこれからどうするかについての不確実性などの要因によるものだと考えています。こうした高い金利により、住宅を購入する人が減少しています。

    また、低金利で購入し後々変更できる変動金利住宅ローン(ARM)の人気が高まっていると指摘しています。住宅建設業者は買い手を引き付けるために低い金利を提供しており、売り手は買い手が金利を下げるために成約費用の手当を提供するなど、住宅ローン金利を下げる取引を行っています。

    住宅ローン金利が約6%に下がるには2024年末までかかる可能性があるため、買い手も売り手も来年は高金利が予想され、譲歩や交渉がより一般的になると推測されています。

    Last week, mortgage rates hit a 23-year high at 7.31%, and this week they remained high at 7.49%. This information comes from Freddie Mac’s Primary Mortgage Market Survey.

    Here are this week’s numbers:

    • The 30-year fixed-rate mortgage is at 7.49%, up from 7.31% last week. A year ago, it was 6.66%.
    • The 15-year fixed-rate mortgage is at 6.78%, up from 6.72% last week. A year ago, it was 5.90%.

    Experts believe these high rates are due to factors like inflation, job market changes, and uncertainty about what the Federal Reserve will do next. These high rates are causing fewer people to buy homes.

    Experts also note that adjustable-rate mortgages (ARMs), which start with lower rates but can change later, are becoming more popular. Homebuilders are offering lower interest rates to attract buyers, and sellers are making deals to lower mortgage rates, such as offering closing cost allowances to help the buyer buy down the rate.

    It might take until the end of 2024 for mortgage rates to come down to around 6%, so both buyers and sellers should expect high rates for the next year, with concessions and negotiations becoming more much more common.

  • ヒューストンの住宅価格

    先日発表されたHAR調査によると、ヒューストン住民の60%近くが、その地域の中央値の価格帯で住宅を購入することが不可能になっていることが発表されました。 現在、ヒューストンの一戸建て住宅価格の中央値は33万9,000ドルとなっています。

    ヒューストン住民の約58%が同じ価格帯でその地域に住宅を購入する余裕があったパンデミック前の状況とは大きな差が出ています。

    例えば、30年の住宅ローンと6.5%の金利で物件を購入した場合、平均で月々 2,400ドル近くを支払うことが予想されます (保険、税金込み)。 これは昨年より月額約170ドル増加しています。

    ヒューストンは、ダラスやオースティンなどの他のテキサスの都市と比較すると、依然としてかなり手頃な価格となっています。 同じ中央価格の住宅を購入するには、ダラスでは年間 136,000 ドル、オースティンでは年間 107,000 ドルの世帯収入が必要となります。

    金利の上昇が続く中の影響と見られています。

    According to a recent report from HAR, nearly 60% of Houstonians cannot afford to buy a house in the median price range in the area. The median price of a single family home in Houston right now is $339,000.

    This is in sharp contrast to pre-pandemic times when nearly 58% of Houstonians COULD afford to buy a house in the area in that same price range!

    Using a 30 yr mortgage and a 6.5% rate as an example, the average family would be expected to pay nearly $2400 per month for a median size home (including insurance and taxes). This is up about $170 per month over last year.

    All this being said, the Houston area is still quite affordable compared to other Texas cities such as Dallas and Austin. Dallas would require a family income of $136,000 per year and Austin $107,000 per year for that same median priced home.

    Rising interest rates continue to be the key factor in these increases.

  • 住宅ローン需要が歴史的水準に低下

    住宅購入者からのモーゲージ(住宅ローン)需要は1995年以来の最低水準に落ち込んでいます。これは金利が上昇しているためであり、人々はインフレを懸念しており、連邦準備理事会は長期にわたる利上げを検討しているためです。 中古住宅販売件数も6月から7月だけで2.2%減少し、前年比16.6%減と大幅に減少しました。 販売可能な住宅が不足し、住宅ローンの金利が購入者にとって有利ではないためです。 住宅ローン銀行協会によると、30年固定金利準拠住宅ローンの平均金利は前週の7.16%から7.31%に上昇しました。 ワオ!

    Demand for mortgages (home loans) from homebuyers dropped to its lowest point since 1995. This is because interest rates are rising, which makes people worried about inflation and causes the Federal Reserve to consider raising rates for a longer period of time. The number of existing home sales also decreased by 2.2 percent from June to July alone, and was a signficant 16.6 percent lower compared to last year. This is because there are not enough homes available for sale and the mortgage rates are not favorable for buyers. According to the Mortgage Bankers Association, the average rate for a 30-year fixed-rate conforming mortgage increased to 7.31 percent from 7.16 percent the previous week. Wow!

  • 住宅保険会社が自然災害補償を中止

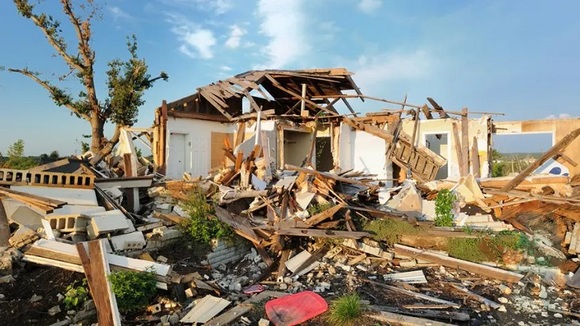
    住宅保険会社は、異常気象のリスクが高い地域で提供する補償を縮小しています。 これは、気候変動により、より頻繁な気象パターンが発生していると考えているためです。 全米保険協会が実施した調査によると、沿岸地域や山火事が発生しやすい地域では、ハリケーン、風、雹による被害は保険で補償されなくなることがわかりました。 オールステート社はハリケーン多発地域での新たな保険を制限する予定で、風や雹による損害については特別な控除や除外を設ける可能性があります。 ハリケーン・イダリアや熱帯低気圧ヒラリーなどの最近の異常気象は、いくつかの州に重大な被害をもたらしました。 マウイ島でも甚大な被害をもたらす山火事が発生し、 過去 3 年間で、米国の保険会社は自然災害保険金として記録的な 2,958 億ドルを支払いました。 2023年上半期だけでも、自然災害による保険損失は400億ドルに上り、史上最も高額な上半期の一つとなりました。 気候変動は気象パターンの変化を引き起こしており、その結果、山火事の季節が長くなり、より頻繁で強力なハリケーンが発生し、竜巻が発生しやすい地域が変化しています。 一部の住宅所有者は保険を見つけることができず、州政府が最終手段として保険を提供しなければなりません。 その結果、住宅所有者は保険を見つけることが困難になり、新規住宅購入者は住宅を購入することが困難となります。

    Home insurance companies are reducing the coverage they offer in areas that are at high risk for extreme weather events. This is because the insurance companies believe that climate change is causing more frequent and severe weather patterns. A survey conducted by the National Association of Insurance Commissioners found that policies will no longer cover damage caused by hurricanes, wind, and hail in coastal areas and regions prone to wildfires. Allstate plans to limit new policies in hurricane-prone areas and may have specific deductibles or exclusions for wind and hail damage. Recent extreme weather events, such as Hurricane Idalia and Tropical Storm Hilary, have caused significant damage in several states. There have also been costly wildfires in Maui. Over the past three years, insurance companies in the US have paid a record $295.8 billion for natural disaster claims. In the first half of 2023 alone, there were $40 billion in insured losses due to natural disasters, making it one of the most expensive first halves on record. Climate change is causing changes in weather patterns, resulting in longer wildfire seasons, more frequent and intense hurricanes, and a shift in tornado-prone areas. Some homeowners are unable to find insurance coverage, and state governments are having to step in to provide coverage as a last resort. This is resulting in homeowners having difficulty finding insurance and new homebuyers having difficulty buying a home for the first time.